0% Interest or Cash? How To Actually Decide On Financing Your Renovation
You’ve got the quote. You know what the kitchen or bathroom remodel will cost. Now comes the question nobody really teaches you how to answer: should you pay for the renovation in cash or take advantage of a 0% financing offer?
Paying cash generally makes sense when you can cover the renovation without draining your emergency savings. A genuine 0% financing offer may be better when you want to preserve cash and can comfortably repay the balance before the promotional rate ends. The better option depends on your savings, monthly budget, financing terms, and how urgently the work needs to happen.
Most homeowners choose whichever option feels less stressful. But paying cash isn’t automatically smarter, and borrowing isn’t automatically a mistake. Here’s how to compare both options before signing a remodeling contract.
When Paying Cash for a Renovation Makes Sense
Cash is often the simplest way to fund a smaller home improvement project. You avoid interest charges, loan applications, and an additional monthly financial obligation.
If the renovation costs $5,000 and you have enough savings to cover it while maintaining a comfortable emergency fund, paying upfront may be reasonable.
Cash can also simplify the payment process, although it doesn’t automatically guarantee a contractor discount.
The Risk of Draining Your Savings
The biggest disadvantage of paying cash is reduced liquidity.
A full kitchen renovation or bathroom remodel can consume a significant portion of your savings. If an unexpected plumbing problem, medical bill, or job interruption follows, you may have less money available.
Before paying cash, consider:
- How much will remain in your savings afterward?
- Can you cover several months of essential household expenses?
- Have you allowed money for unexpected remodeling costs?
- Would an emergency force you to borrow at a higher interest rate?
You should also account for renovation cost overruns. Hidden water damage, plumbing changes, and unforeseen electrical work can increase the final bill.
For more homeowner project-planning advice, explore HomeYardo’s Home Improvement guides.
When 0% Financing Actually Makes Sense
Some homeowners avoid financing because they associate borrowing with expensive interest. Others accept a promotional offer without considering what happens when the introductory period expires.
Neither approach tells you whether the financing is suitable.
A promotional loan can help you complete a renovation while preserving savings for other expenses. However, the actual benefit depends on its repayment conditions.
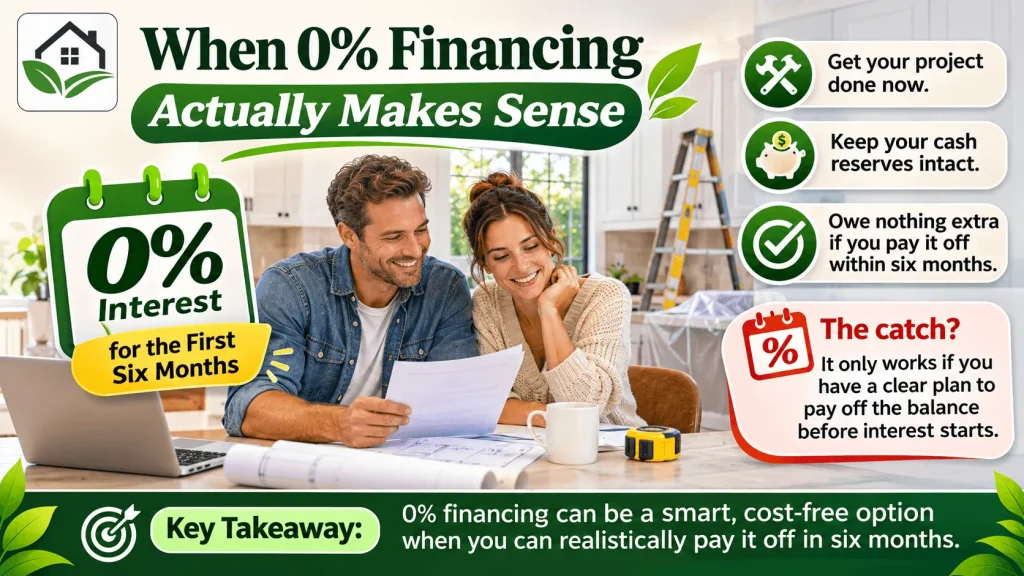
For example, a contractor may advertise 0% interest for the first six months. Before relying on that advertised period, confirm the current offer directly with the provider and obtain the lender’s written terms. Promotional periods and eligibility can change.
House Transformers’ financing page currently describes a different arrangement: 0% interest and no payments for the first 12 months, subject to credit approval and lender terms.
The distinction matters because an offer advertised as interest-free may not work the way you expect.
Understand True 0% APR vs. Deferred Interest
Before accepting renovation financing, determine which type of promotion is being offered.
| Financing type | How it works | Main risk |
|---|---|---|
| True 0% APR | No interest accrues during the introductory period | Interest may apply to the remaining balance after the promotion |
| Deferred interest | Interest may accrue but is waived if the balance is paid in full by the deadline | Missing the payoff deadline can trigger interest dating back to the original transaction |
| Standard installment loan | Interest is charged according to the loan agreement | Total repayment costs can be substantially higher than the amount borrowed |
A deferred-interest agreement is not equivalent to a true 0% APR loan.
Read the full agreement, including any origination fees, late-payment conditions, promotional expiration dates, and the interest rate that applies afterward.
A loan with 0% interest but a substantial upfront fee isn’t necessarily free financing.
A Simple Way to Decide: Cash or Financing?
Ask yourself three questions before choosing how to pay for your renovation.
1. Can You Repay the Balance Before the Promotional Period Ends?
Suppose you’re financing a $12,000 remodel with six months of genuine 0% APR financing and no additional fees.
You would need to repay approximately $2,000 per month to eliminate the balance within that period.
If your monthly budget cannot reliably handle that payment, the introductory offer may not be the best fit.
The advertised minimum monthly payment may be much lower than the amount needed to pay off the full balance before the promotion expires.
2. Would Paying Cash Leave You Without Emergency Savings?
If paying cash would leave you financially exposed, preserving your savings may justify considering financing.
However, financing only helps if the monthly payments are affordable.
Borrowing money to preserve an emergency fund doesn’t make sense if the repayment obligation creates a new financial emergency.
3. Is the Renovation Urgent or Optional?
A failing roof, serious plumbing leak, or damaged bathroom may require prompt repairs.
Cosmetic upgrades, such as replacing functional cabinets or installing decorative finishes, are usually easier to postpone.
An urgent repair can strengthen the case for financing when cash is limited. Still, urgency doesn’t make an expensive loan affordable. Compare available options and separate necessary repairs from optional improvements wherever possible.
Cash vs. Financing: Quick Comparison
| Situation | Option worth considering |
|---|---|
| You have sufficient cash and emergency savings | Pay cash |
| You qualify for genuine 0% APR financing and can repay on time | Consider financing |
| Paying cash would empty your emergency fund | Consider partial financing or reducing the project scope |
| Monthly payments would strain your budget | Save more, reduce costs, or postpone nonurgent work |
| The renovation is an urgent safety or repair issue | Compare affordable financing options |
| The financing includes high fees or expensive post-promotion rates | Compare the total cost against paying cash |
There is no universal winner. The better choice is the one that meets the project’s needs without creating unnecessary financial risk.
The Middle Option Nobody Talks About
You don’t have to choose between paying the full amount upfront and borrowing the entire renovation cost.
For a larger project, such as a combined kitchen and bathroom remodel, some homeowners prefer a combination of cash and financing.
Imagine a $20,000 renovation:
- Total renovation cost: $20,000
- Cash down payment: $8,000
- Amount financed: $12,000
- Six-month repayment target: $2,000 per month
This example assumes a genuine 0% APR promotion, no financing fees, and no other charges.
Paying part of the cost upfront reduces the loan balance and the amount you need to repay. It also leaves some cash available for emergencies, provided the initial payment is affordable.
Before choosing this arrangement, ask whether the lender allows partial financing and whether the promotional terms change with the amount borrowed.
What To Check Before Accepting Renovation Financing
Even when a contractor offers attractive financing, the written agreement should determine your decision.
Check the promotional APR, expiration date, regular interest rate, repayment schedule, financing fees, and consequences of missed payments.
You should also confirm whether payments begin immediately, whether a down payment is required, and whether the loan has any prepayment penalties.
Keep the financing agreement separate from the contractor’s project contract. Both should clearly describe what you’re agreeing to.
For homeowners planning repairs and upgrades, HomeYardo’s Maintenance guides offer related information about maintaining and improving the home.
Final Takeaway: Which Renovation Payment Option Is Better?
Cash is usually a straightforward choice when you can afford the renovation without compromising your financial safety net.
A genuine 0% financing plan can be useful when you want to keep savings accessible and have a realistic repayment strategy.
For larger projects, combining cash and financing may offer a workable middle ground.
Whatever you choose, compare the full repayment cost, protect your emergency reserves, and make sure your contractor and lender explain the terms before you commit.
FAQ’s
Paying cash can be better when you have sufficient savings and want to avoid debt. Financing may be preferable when preserving emergency funds matters and the repayment terms fit your budget. Compare the total cost and the effect on your cash reserves.
A genuine 0% APR promotion does not accrue interest during its specified introductory period. Deferred-interest offers work differently and may charge accrued interest retroactively if you fail to repay the full promotional balance by the deadline. Some offers may also include fees.
Using savings may make sense if you can pay for the kitchen renovation while retaining enough money for emergencies and other financial obligations. Avoid committing your entire cash reserve to a nonessential project.
With a true introductory 0% APR plan, the regular interest rate generally applies to the unpaid balance after the promotion expires. With deferred-interest financing, failing to pay the balance in full by the deadline may cause previously accrued interest to become payable.
Yes, if the contractor and financing provider allow it. Paying part of the project cost upfront reduces the amount borrowed and may lower the required monthly payments or shorten the repayment period.
It can. A financing application may involve a hard credit inquiry, and the new debt, repayment history, and credit utilization can affect your credit score. The impact depends on the financing product and how it is reported.
Ask about the APR, fees, promotional deadline, monthly payment, total repayment amount, late-payment consequences, prepayment penalties, and whether the offer involves deferred interest. Request the complete terms in writing before signing.
Financing may be necessary when a serious repair cannot safely wait and available cash is insufficient. Compare financing costs, consider whether insurance may cover the damage, and prioritize necessary work over optional upgrades.